Our Difference
Our Portfolios
Investment portfolios carefully constructed and managed by our team
To help ensure our clients are properly invested based upon the goals and objectives of their financial plans, we've committed ourselves to meeting the challenges of an ever-changing marketplace and economic landscape. That's why you'll find investment portfolios that we carefully construct and manage ourselves at the heart of the investment services we provide for our clients.
We offer a total of six portfolio strategies: three allocation strategies and three fixed strategies, one of which is completely customizable for clients with specific requirements. Determining the best strategy choice for a client depends on investment objective, time horizon, risk tolerance, income requirements, past experience and outlook – information that is carefully detailed during the financial planning process.
Allocation Strategies
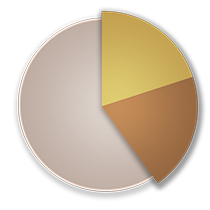
Conservative Strategy
Designed to generate income and minimize principal volatility over the intermediate term.
- - Suitable for investors with large portfolios, lower risk tolerance, or a shorter time frame
- - 40% – 60% of assets in dividend-paying equities*
- - 40% – 60% in fixed income and cash alternatives
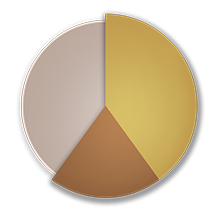
Balanced Strategy
Seek longer-term total return through a balance of income and growth.
- - Interest, dividends, and capital appreciation have equal importance
- - Designed for investors who want higher long-term returns while managing volatility
- - 40% – 60% of assets in equities*
- - 40% – 60% in fixed income and cash alternatives
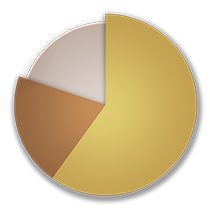
Growth Strategy
Designed to focus on long-term capital appreciation while managing risk.
- - Owns higher-yielding dividend stocks and a fixed income allocation for risk management
- - Best suited for investors with a longer time frame and higher risk tolerance
- - 60% – 80% of assets in equities*
- - 20% – 40% in fixed income and cash alternatives
Fixed Strategies
Capital Appreciation Strategy
Seeks to invest in companies with higher-than-average revenue, earnings, and dividend growth.
- - Core holdings selected using a top-down approach and fundamental analysis
- - Peripheral holdings added via bottom-up approach for higher returns on equity and capital
- - Disciplined buy and sell targets remove the emotional component of investing
- - May include mutual funds or ETFs to satisfy equity allocations
- - Sector and asset class weightings adjusted to reflect market and economic conditions
- - Best suited for investors focused on long-term capital growth who have a higher risk tolerance and a longer investment horizon
Equity Income Strategy
Designed to generate significant dividend income while allowing for capital appreciation.
- - Focuses on companies paying above-average dividends with potential for dividend growth
- - Evaluates individual company fundamentals
- - Portfolio holdings balanced to track sector weightings of the broad market
- - Dividends may comprise a meaningful portion of total investor allocation
- - Ideal for investors seeking consistent income through dividends, such as retirees or those nearing retirement, who also desire potential for capital appreciation
Custom Strategy
Built for clients with special investment considerations or unique requirements.
- - Ideal for clients with large low-cost-basis stock positions or complex needs
- - We develop a personalized investment policy matching your objectives and risk tolerance
- - Discretionary management frees you from day-to-day investment decisions
- - Our team manages asset allocation and tax consequences of trading on your behalf
*The above represents target allocation of the advertised strategies. Individual clients accounts may vary from the allocation over time based on various factors, including the client's unique circumstances.
Important Disclosures
General Investment Disclosures
Any opinions are those of the Investment Manager(s) and their team and not necessarily those of Raymond James. Opinions are subject to change at any time without notice. Content provided herein is for informational purposes only and should not be used or construed as investment advice or a recommendation regarding the purchase or sale of any security outside of a managed account. This should not be considered forward looking, and does not guarantee the future performance of any investment.
Fee-Based Account Disclosure
In a fee-based account, clients pay a quarterly fee, based on the level of assets in the account, for the services of a financial advisor as part of an advisory relationship. In deciding to pay a fee rather than commissions, clients should understand that the fee may be higher than a commission alternative during periods of lower trading. Advisory fees are in addition to the internal expenses charged by mutual funds and other investment company securities. To the extent that clients intend to hold these securities, the internal expenses should be included when evaluating the costs of a fee-based account. Clients should periodically re-evaluate whether the use of an asset-based fee continues to be appropriate in servicing their needs. A list of additional considerations, as well as the fee schedule, is available in the firm's Form ADV Part 2 as well as the client agreement.
Risk & Suitability
All investments are subject to risk, including loss. There is no assurance that any investment strategy will be successful. Asset allocation and diversification does not ensure a profit or protect against a loss. It is important to review the investment objectives, risk tolerance, tax objectives and liquidity needs before choosing an investment style or manager.
This is not intended to be a client-specific suitability analysis or recommendation. Do not use this as the sole basis for investment decisions. Do not select an investment strategy based on performance alone.
Mutual Fund Risk
Every type of investment, including mutual funds, involves risk. Risk refers to the possibility that you will lose money (both principal and any earnings) or fail to make money on an investment. Changing market conditions can create fluctuations in the value of a mutual fund investment. In addition, there are fees and expenses associated with investing in mutual funds that do not usually occur when purchasing individual securities directly.
ETF & Mutual Fund Disclosure
These strategies may contain Exchange Traded Funds (ETF) and/or Mutual Funds. Investors should carefully consider the ETF and mutual fund investment objectives, risks, charges, and expenses before investing.
The prospectus contains this and other information and can be obtained from the ETF or Mutual Fund sponsor as well as from your financial advisor. The prospectus should be read carefully before investing.
ETF shareholders should be aware that the general level of stock or bond prices may decline, thus affecting the value of an exchange-traded fund. Although exchange-traded funds are designed to provide investment results that generally correspond to the price and yield performance of their respective underlying indexes, the funds may not be able to exactly replicate the performance of the indexes because of fund expenses and other factors.
Equities & Fixed Income
Equities: Investors should be willing and able to assume the risks of equity investing. The value of a client's portfolio changes daily and can be affected by changes in interest rates, general market conditions and other political, social and economic developments, as well as specific matters relating to the companies in which the strategy has invested. Companies paying dividends can reduce or cut payouts at any time.
Fixed Income: All fixed income securities are subject to market risk and interest rate risk. If fixed income securities are sold in the secondary market before maturity, an investor may experience a gain or loss depending on the level of interest rates, market conditions and the credit quality of the issuer. There is an inverse relationship between interest rate movements and bond prices. Generally, when interest rates rise, bond prices fall and when interest rates fall, bond prices generally rise. Please note these strategies may be subject to state, local, and/or alternative minimum taxes. You should discuss any tax or legal matters with the appropriate professional.
Sector Concentration Risk
Strategies that invest primarily in securities of companies in one industry or sector are subject to greater price fluctuations and volatility than strategies that invest in a more broadly diversified strategies. The Strategy may have over-weighted sector and issuer positions and may result in greater volatility and risk. Investing in small cap stocks generally involves greater risks, and therefore, may not be appropriate for every investor. The prices of small company stocks may be subject to more volatility than those of large company stocks.
Get Started
Find the Right Portfolio for You
Schedule a consultation to discuss which portfolio strategy aligns with your goals, risk tolerance, and time horizon.